Services Jet Specs Membership New Markets Vision News Contact Partnership →
ZZOAH.com → TheFinestSchool.com →
Private Jets Korea — Premium Aviation Services
Private Jets of Korea · Est. 2020 · 5+ Years Field-Proven

Time, Reclaimed.
Distance, Dissolved.

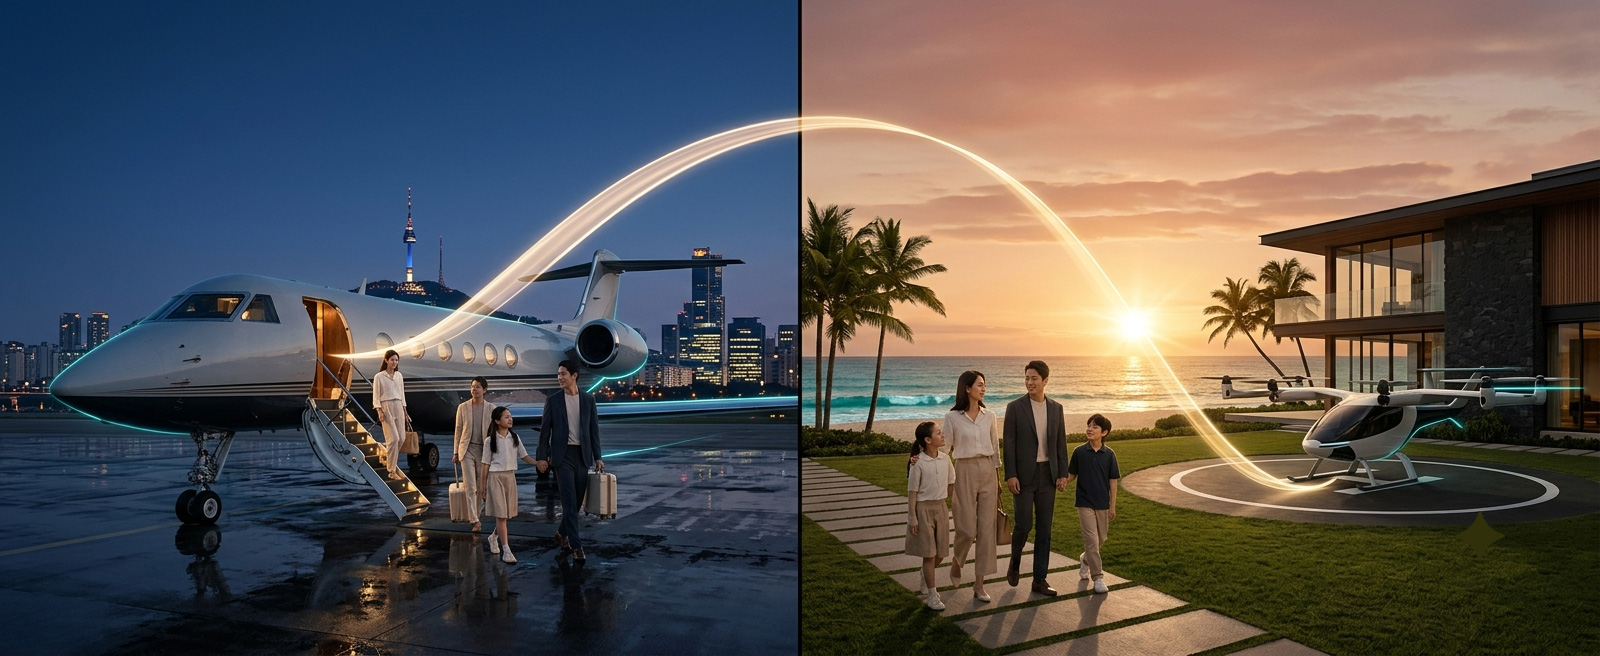
Korea's premier private aviation and luxury mobility platform. Charter, acquisition, fractional ownership — and the gateway to the one asset flights can't refund.

Intelligence & Analysis Latest from PrivateJets.kr
The Finest School — Global Education Platform Intelligence Brief
Education Platform Intelligence · Access Controlled · 2026
The World's First AI-Integrated Global Education Platform
How The Finest School operates across four geographies — Massachusetts, Hawaii, Korea, India — without building a single conventional school. 15-chapter strategic brief. For qualified partners only.
FBO Intelligence Brief — Access Controlled
FBO Intelligence · Access Controlled · 2026
The World's First Corporate-Customised FBO Operating Model
A new model that eliminates structural airport deficits without a single additional flight. 16-chapter strategic brief. For qualified partners only.
The Living World — AI Platform Intelligence Brief
The Living World · AI Platform Intelligence · Access Controlled · 2026
One App. Five Identities. One Life.
The world's first persistent AI game world built from a real global network — community, shopping, social, mobility, and AI life progression in one platform. 13-chapter strategic brief. For qualified partners only.
Sky Without Borders — Five-Market Aviation Strategy Intelligence Brief
Sky Without Borders · Aviation Strategy Intelligence · Access Controlled · 2026
Five Markets. One Sky. No Borders.
A confidential five-market private aviation strategy spanning Korea, India, Singapore, Vietnam, and Thailand — built on access no charter price can buy. 12-chapter strategic brief. For qualified partners only.
Dominance Without Monopoly — Global Lifestyle OS Intelligence Brief
Dominance Without Monopoly · Platform Strategy Intelligence · Access Controlled · 2026
The Position That Cannot Be Assembled Later.
Why the global #1 platform is more unassailable than the global #1 manufacturer — and why GLO has already crossed the threshold where no regulator can touch it. 8-chapter strategic brief. For qualified partners only.
Stablecoin as Infrastructure — Intelligence Brief
Stablecoin as Infrastructure · Payment Intelligence · Access Controlled · 2026
The Next Global Payment Standard Is Already Here.
Why stablecoins are the payment infrastructure of the AI-driven global economy — and why GLO and its strategic partner are positioned at the exact intersection where it lands. 9-chapter strategic brief. For qualified partners only.
Sustainable by Design — Intelligence Brief
Sustainable by Design · Business Architecture Intelligence · Access Controlled · 2026
Built to Compound, Not Built to Launch Once.
Why AI-era education, mobility, residency, travel and business space become a durable, high-value, de facto-dominant business without ever needing to behave like a monopoly. 13-chapter strategic brief. For qualified partners only.
Relocation of Life — Intelligence Brief
Relocation of Life · Wealth Migration Intelligence · Access Controlled · 2026
Status Is Purchasable. Life Is Not.
A record 165,000 millionaires will relocate in 2026. Every one can buy legal status; almost none can buy the uninterrupted continuation of their family's life. The platform built to close that gap. For qualified partners only.
The Longevity Layer — Intelligence Brief
The Longevity Layer · Medical & Longevity Intelligence · Access Controlled · 2026
Health That Travels With the Member.
67% of UHNWIs rank healthspan above returns. Every provider serving them is anchored to a building or a phone. The layer that moves with the member instead. For qualified partners only.
The Talent Infrastructure — Intelligence Brief
The Talent Infrastructure · Corporate Talent Intelligence · Access Controlled · 2026
The Number Gets Them to the Table. The Life Gets Them to Say Yes.
In the AI-era war for talent, money has stopped differentiating. What wins the person is whether their family's life works, anywhere. GLO is that weapon. For qualified corporate and capital partners only.
Property OS — Intelligence Brief
Property OS · Real Estate Intelligence · Access Controlled · 2026
Family Offices Are Fleeing Real Estate. The Service Layer On Top Is Booming.
Real estate allocation has fallen from 14% to 8% since 2019 — while branded residences and concierge property services grow faster than the asset class itself. The coordination layer built for exactly that divergence. For qualified partners only.
The Global Stage — Intelligence Brief
The Global Stage · Entertainment Intelligence · Access Controlled · 2026
K-pop's Biggest Year Is Also Its Most Physically Unsustainable.
110+ stadium shows from two acts alone — while trainee numbers fall 38.3% and idols withdraw over health at a documented, rising rate. The life-support infrastructure the industry outgrew. For agencies and qualified partners only.
Borderless by Design — Intelligence Brief
Borderless by Design · Education & Immigration Intelligence · Access Controlled · 2026
America Tightened the Student Visa. GLO Families Never Held One.
DHS's July 2026 rule caps F-1/J-1 status at four years — a real problem even for UHNWI families with EB-5 or Gold Card capital. Why The Finest School's four-hub model was never dependent on any single country's visa system. For qualifying families and partners only.
Above the Machine — Intelligence Brief
Above the Machine · Low-Altitude Economy Intelligence · Access Controlled · 2026
China Is Building a Trillion-Dollar Fleet. GLO Already Owns the Life It Serves.
RMB 3.5 trillion by 2035 in state-backed low-altitude economy investment — while Europe's two best-funded eVTOL makers burned an estimated €3 billion and collapsed within months of each other. Why a vehicle is a component, not a business model. For manufacturers, investors, and qualified partners only.
The Orchestration Layer — Intelligence Brief
The Orchestration Layer · Concierge & Crisis Coordination Intelligence · Access Controlled · 2026
Seventeen Institutions. One Family. No One Built to Connect Them.
From emergency medical evacuation to daily lifestyle execution, no single institution — not 911, not a private bank, not a concierge firm — is built to coordinate a globally mobile family's full life. Why GLO's ninth architecture layer closes that gap. For qualifying families and partners only.
School Framework
The Finest School · World First · 2026
The World's First AI-Integrated International School Framework — Agreed.
Multiple US elite private schools. Four delivery modes. Six customisation axes. Education that travels with the family. H1 2027 signing.
Elite School Partnership Intelligence
The Finest School · Physical AI · Partnership Intelligence · 2026
Why the World's Best Schools Are Waiting for This Platform.
Physical AI finds its fastest commercial path through education. The wall stopping everyone else does not exist here. The logic took 26 years to build.
eVTOL · Analysis
The eVTOL Race to Market
Joby · Archer · EHang · Eve — specs, certification & official flight videos.
Property OS · Residential
Only one platform rents you the life.
East Hampton, New York — the future of luxury residential living.
Property OS · Commercial
Your business travels with you. Now, so does your life.
432 Park Avenue, Manhattan — work and live without separation.
Companion Logistics · Global
The cargo travels with you. Not separately.
Pets · Art · Luxury goods · Confidential cargo · Fashion · Customs end-to-end.
Airport & FBO Guide · 2025
USA Top 25 · Europe Top 50 Private Jet Airports
Complete airport & FBO reference — rankings, facilities, and intelligence for every major hub.
Vision · Evidence-Based
The Boundaries Are Collapsing.
6 boundary collapses already underway — data, markets, and why the timing is now.
Mobility Intelligence · 2026
Autonomous EVs — Opportunity or Disruption?
Evidence-based analysis: market reality, negative case, industry impact & our optimal business model.
Market Intelligence · 2026
Who Our Clients Are. And Why They Need Us.
Age data, market size, Korea & India analysis, education scandals — the evidence-based client case.
FBO Hub · Global Strategy
The FBO Reimagined as a Lifestyle Hub.
From aviation facility to life command center — medical, education, logistics, security, mobility.
Competitive Intelligence · 2026
Every leader does one thing. We do all eight.
20 platforms, 8 sectors — and why none of them compete with us.
Investment Intelligence · 2026
Maximum Value. Minimum Capital at Risk.
Five pillars, eight revenue layers, zero speculative commitment — the GLO capital efficiency model.
AI & Labour · Structural Design · 2026
AI Without the War.
Every industry fighting AI labour conflict. GLO was designed from day one to avoid it entirely — partners are elevated by AI, not threatened by it. Updated June 2026.
The Finest School · The Mission · AI Era Education
The Student Who Writes the Textbook.
Grade 4 to graduation — one real-world mission per year. One book. One documentary. Presented to a global audience. Nine years. Nine works. A portfolio no university has seen before.
AI & Life · Technology as Backbone · 2026
The Backbone Is Theirs. The Life Is Yours.
NVIDIA, Hyundai, Boston Dynamics, Google — building the future of AI. We are already living in the result, designing the life our members want inside it.
Wealth Migration · Global Intelligence · 2026
Where Do You Go When the World Changes?
142,000 millionaires relocated in 2025. UK tax exodus, China crackdown, Korea crisis — GLO moves not just you, but your entire life. With legal residency handled.
Research & Intelligence · 2026
The Evidence Is Now Impossible to Ignore.
15 reports on why the AI era is dismantling education as we know it — and what comes next.
Who We Are

The operational foundation
of a global platform.

"This platform was not designed from the outside. It is the natural product of 26 years of field-built education networks and 5+ years of live private jet operations — accumulated, iterated, and market-optimised until the integrated model became inevitable."

Private Jets of Korea is the operational core of Global Lifestyle OS — the world's first hyper-personalised integrated mobility ecosystem platform. Five years of live private aviation operations across Korea and Asia Pacific. 26 years of direct relationships with 100+ US elite private schools. This is not a business plan. It is a field-proven platform with a global architecture already in motion.

The founder spent five years in the real conditions of Korea and Asia Pacific private aviation — not studying the market, but operating in it. Every aircraft type, every client profile, every regulatory friction point, every operational failure and success is embedded in the model we operate today. That experience is the infrastructure upon which the Global Lifestyle OS is being built. The boundaries between aviation, education, property, and logistics are collapsing. No single-sector operator can follow where this platform is going.

Years of Operations
5+
Real-world private aviation operations across Korea and Asia Pacific. Charter, acquisition, fleet management — all field-proven in live market conditions.
US Elite School Network
26 yrs
100+ US elite private school direct partnerships — the education infrastructure that cannot be bought with capital or built with time alone.
Expansion Markets
5
Korea · India · Singapore · Vietnam · Thailand — the Phase I corridor of the Global Lifestyle OS four-stage global expansion strategy.

3.88 million private jet departures globally in 2025 — an all-time high, 34% above pre-pandemic levels. 713,626 UHNWI individuals controlling $59.8 trillion in assets. 142,000 millionaires relocated their primary residence in 2025 — and every one of those relocations created a mobility, education, and logistics challenge. These are our clients — and this is why they need us.

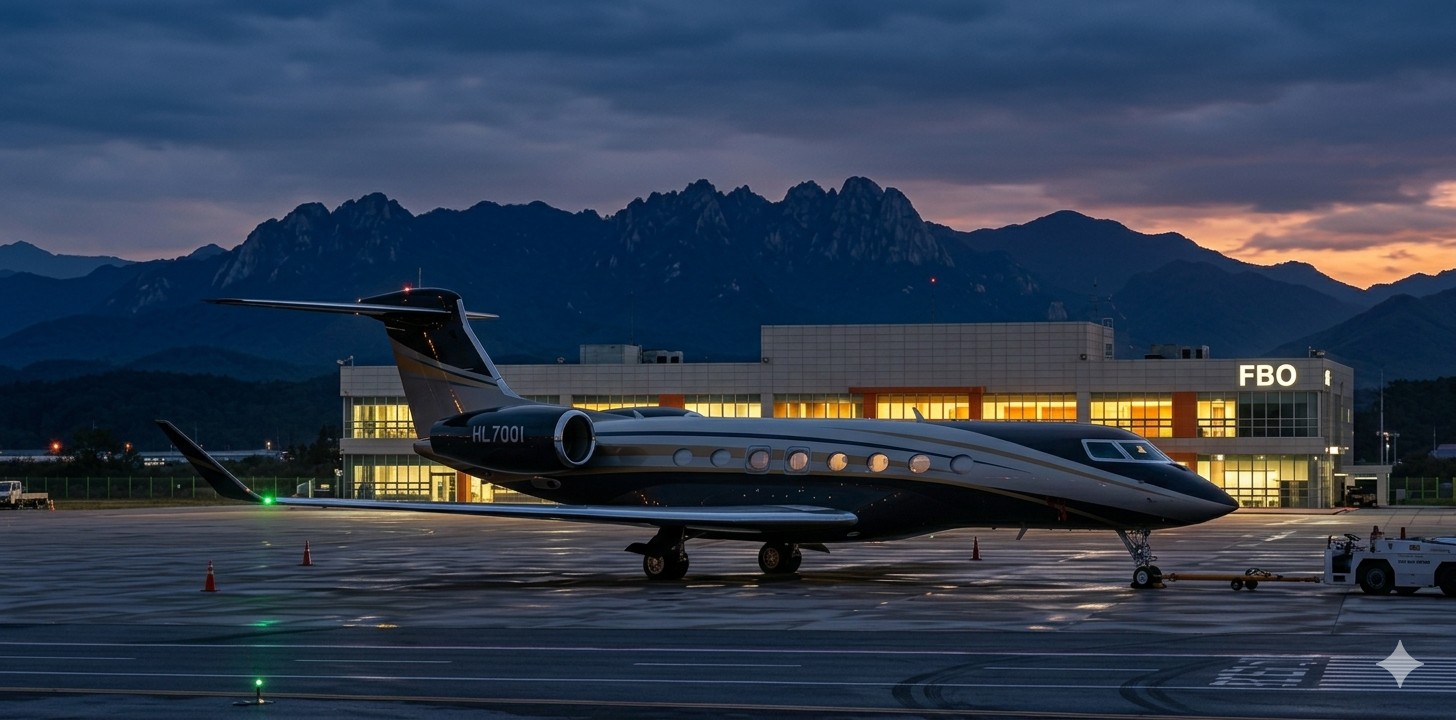
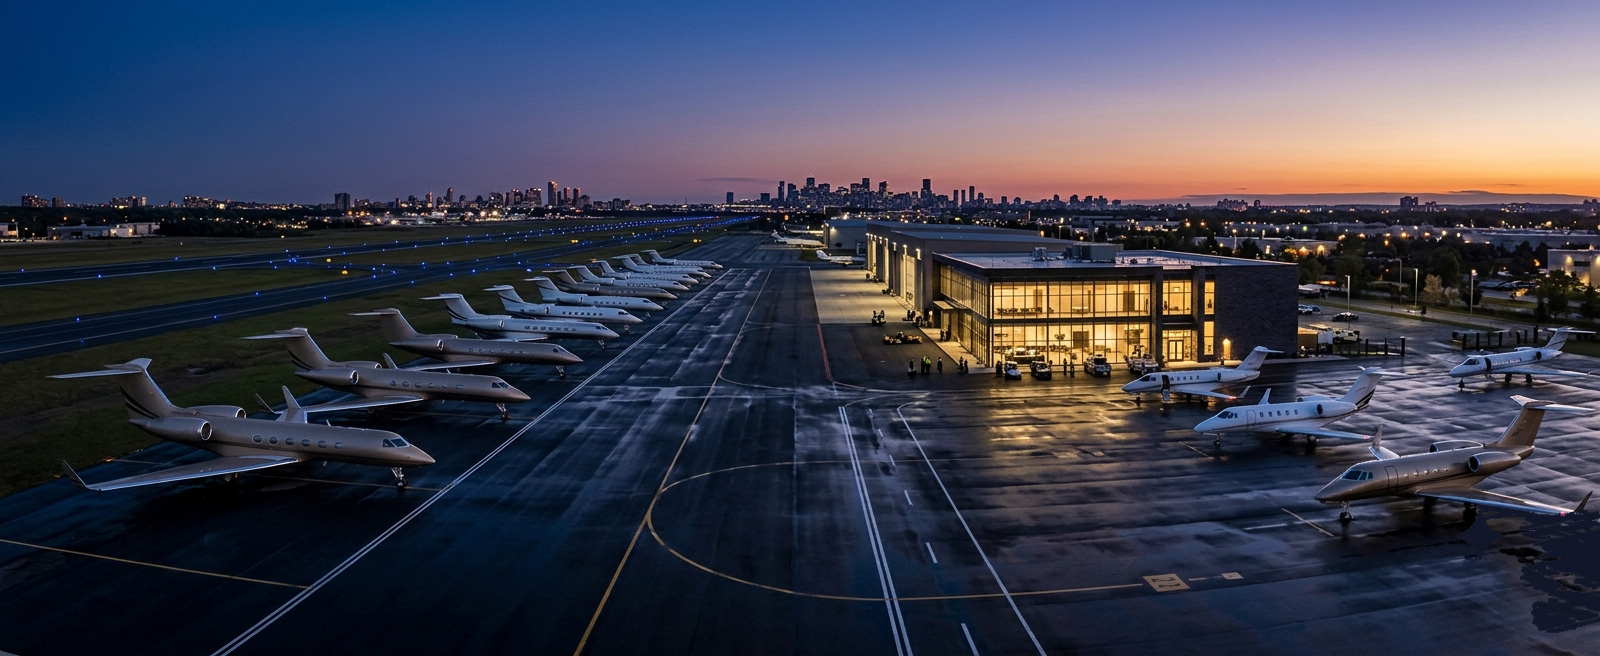
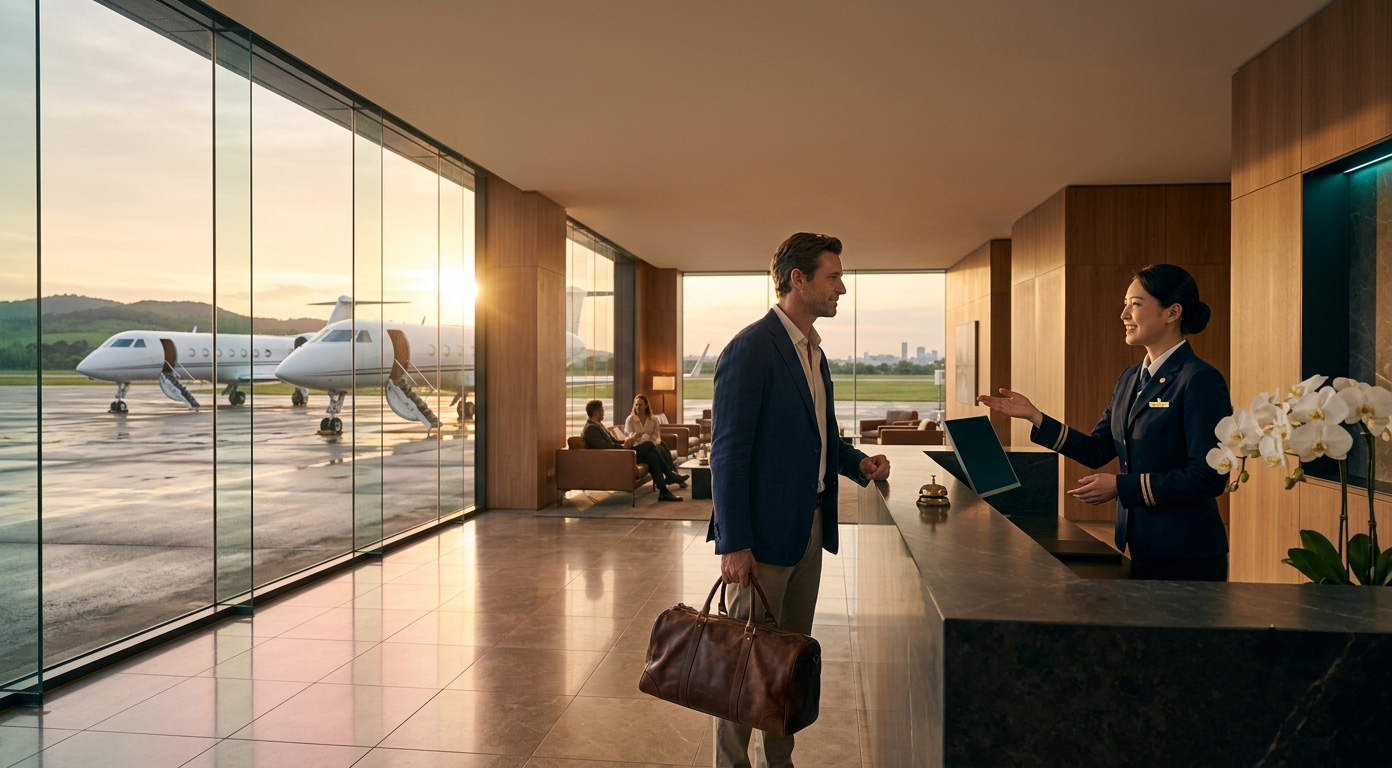
Seoul Gimpo Business Aviation Center — Private Jet Fleet
Korea & Asia Market

The anchor hub
for a five-country corridor.

Korea is not simply one market. It is the operational anchor for a five-country Asia Pacific expansion that forms Phase I of the Global Lifestyle OS global strategy. The supply imbalance in Korea's private aviation market — acute demand for light and midsize jets against critically short supply — is the structural gap that five years of field operations have positioned us to close. And from that foundation, the corridor extends: India, Singapore, Vietnam, Thailand.

Korea's private jet flight activity rose 13% year-over-year as of 2026. The global business jet market is on track to surpass $33.1 billion in 2026. First-time private jet flyers are younger — 47% are now under 45 — and the shift toward charter and access-based models over outright ownership validates exactly the platform architecture we have built here. For qualified partners: the five-market aviation strategy is available in a dedicated strategic brief.

MarketStatusStrategic Role
KoreaOperational — privatejets.kr livePhase I anchor hub. FBO strategy centred on Yangyang. eVTOL integration 2026–2027. Autonomous EV corridor Seoul–Yangyang.
IndiaPhase I — INDUS-MATRIXFastest-growing UHNWI market. 4 hub sequential launch. The strategic partner market with the highest long-term ceiling.
SingaporePhase I — INDUS-MATRIX anchorGlobal Investor Programme. MAS stablecoin framework active. Primary Southeast Asia financial hub.
VietnamPhase IFastest-growing economy in SE Asia. Manufacturing and tech UHNWI expansion. Emerging private aviation demand.
ThailandPhase IEstablished UHNWI residential base. Elite international school investment surging. Natural education + mobility integration.
The Korea Market Reality
  • Light and midsize jets represent the majority of corporate demand — yet supply is acutely short. Clients are forced into larger, more expensive aircraft. We are closing this gap.
  • Korea is the first FBO Hub in the Global Lifestyle OS network — reimagined as a lifestyle hub, not just an aviation facility. Aviation is operating today; medical, education, logistics, and security are being built into the same node.
  • The Korea anchor validates the model before it scales to India, Singapore, Vietnam, and Thailand. The USA Top 25 and Europe Top 50 private jet airport network completes the global coverage.
Our Services

Five services.
One integrated platform.

Each service stands alone as a world-class offering. Together, they form the operational foundation of the Global Lifestyle OS ecosystem.

Private Jet Charter Service
Service 01
Private Jet Charter

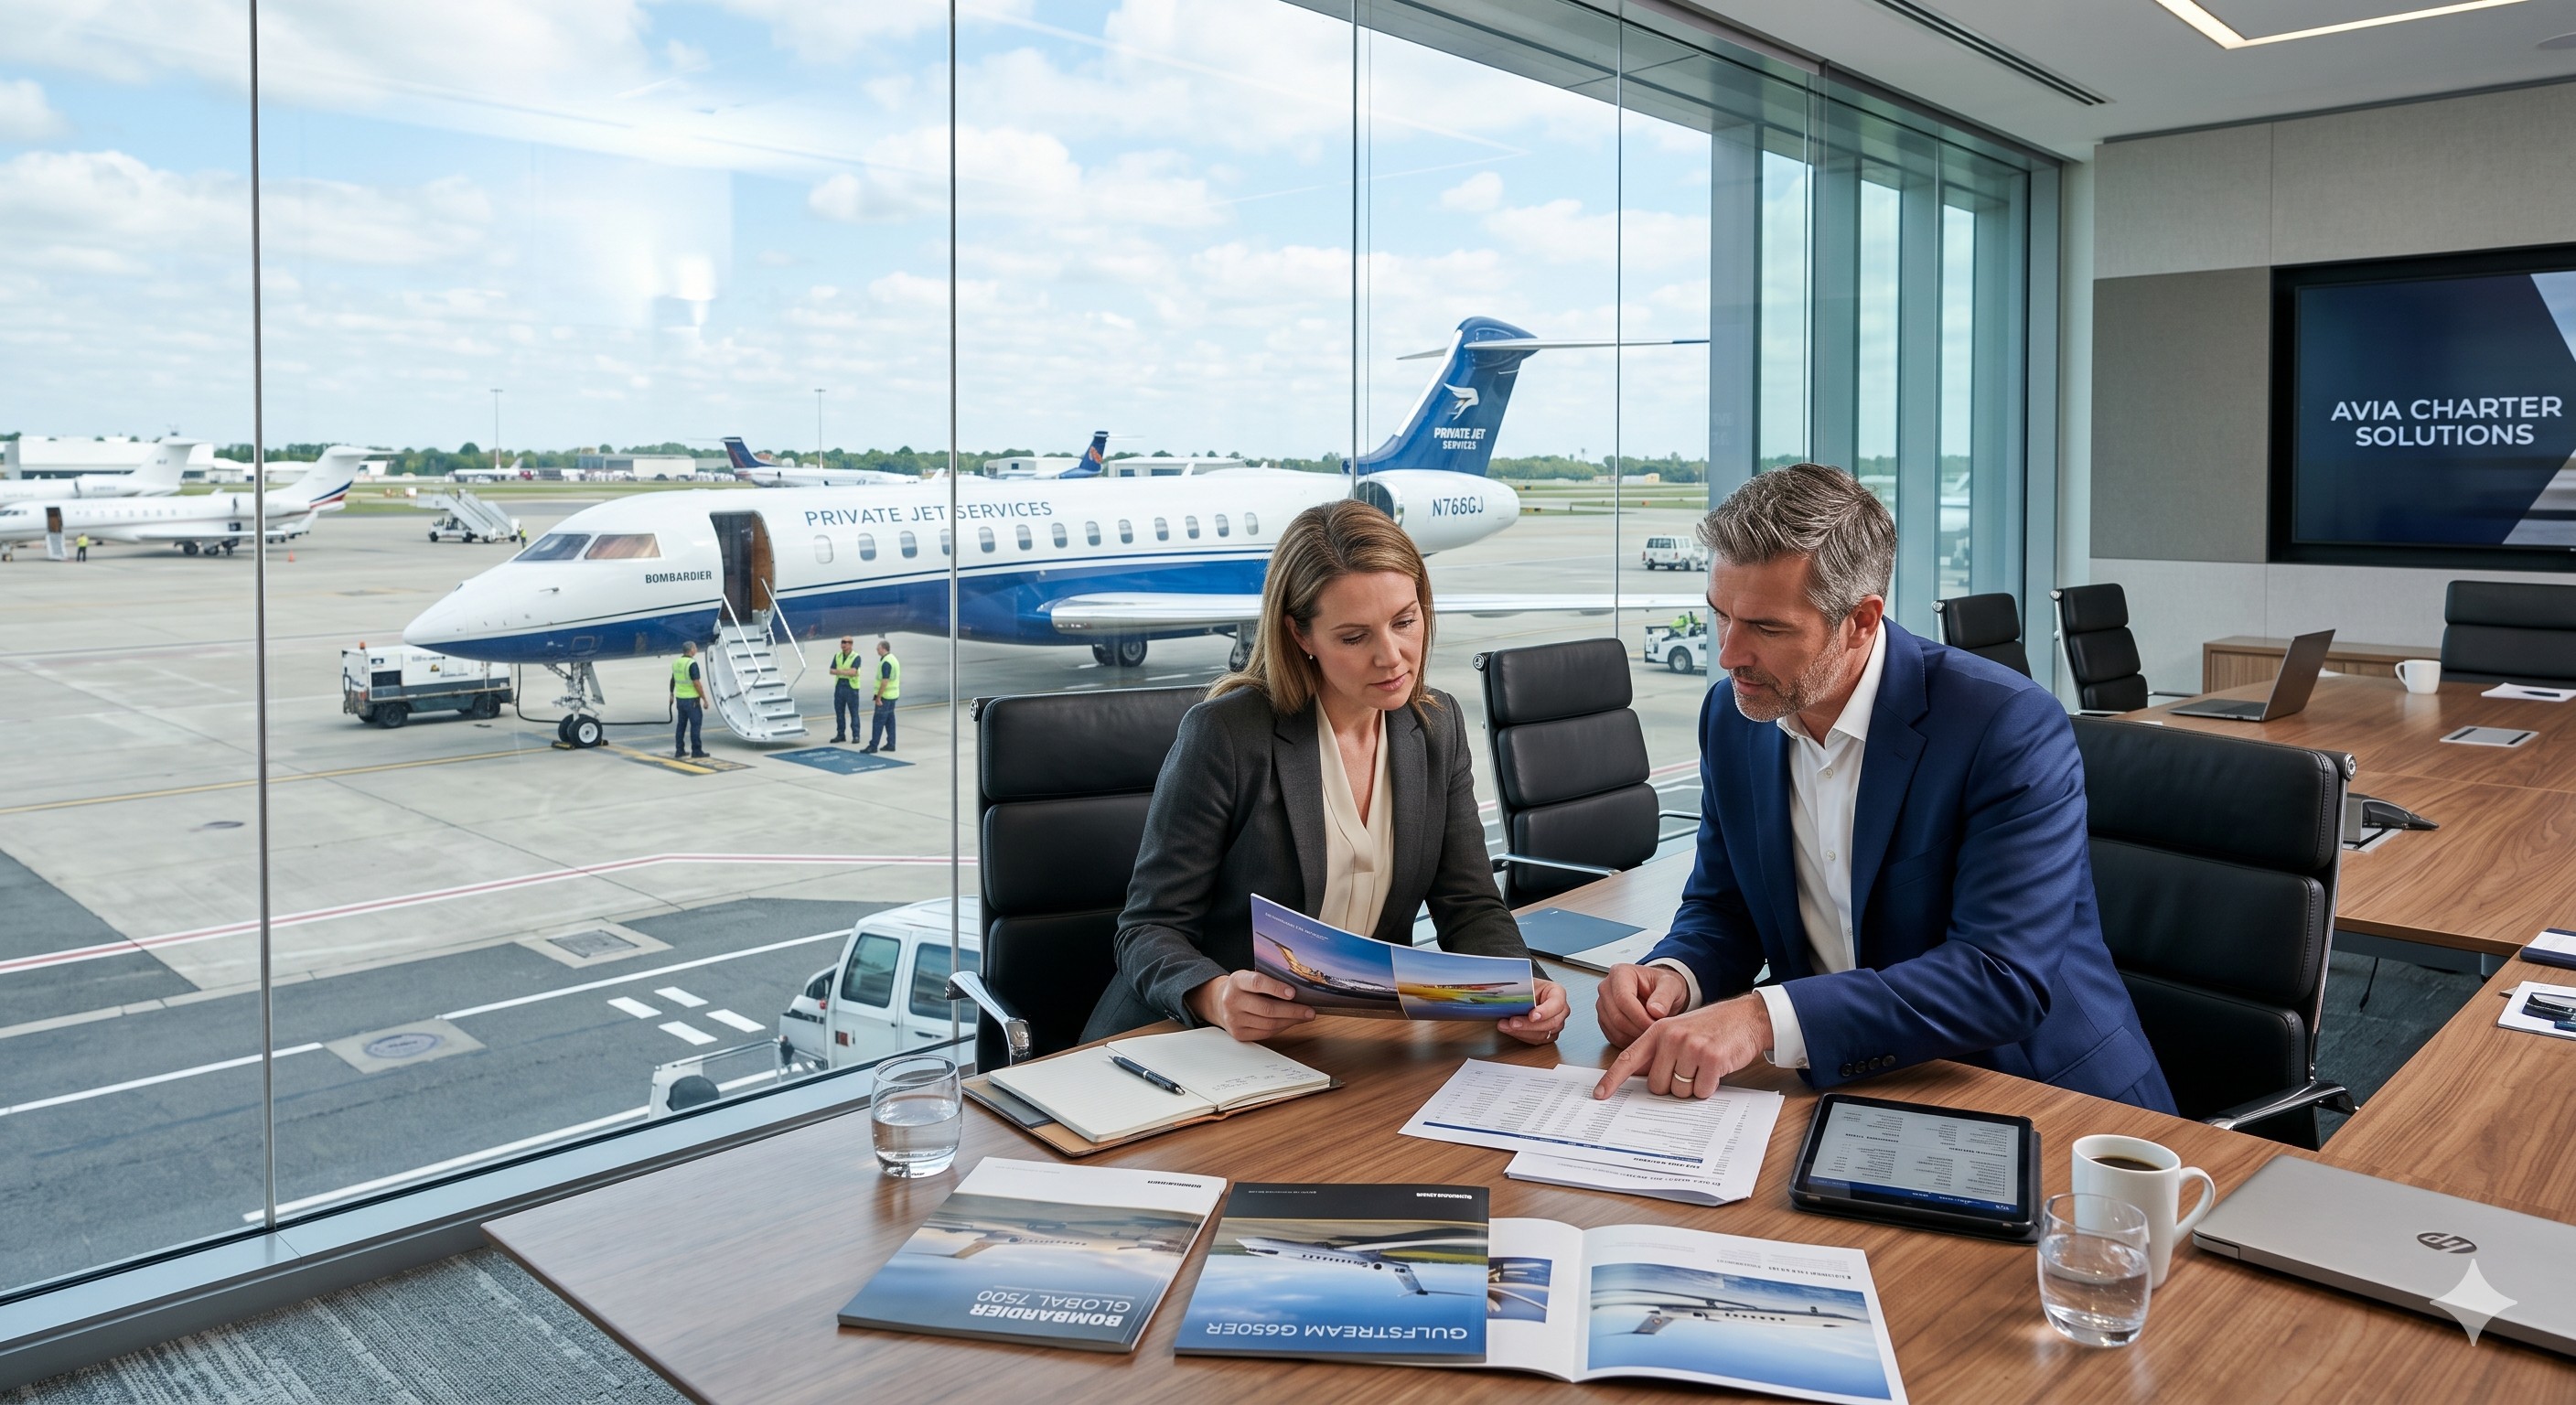
Access to the full spectrum of private aviation — from light jets for regional hops to ultra-long-range aircraft for intercontinental travel. Both brokered and directly operated aircraft. Optimized aircraft matching for every mission profile.

Private Jet Acquisition & Advisory
Service 02
Acquisition & Advisory

Aircraft selection, purchase negotiation, registration, and ongoing management. From first enquiry to wheels-up ownership. Five years of real market data — not theoretical analysis — guides every recommendation.

Yacht & Leisure Venue Brokerage
Service 03
Yacht & Leisure Venues

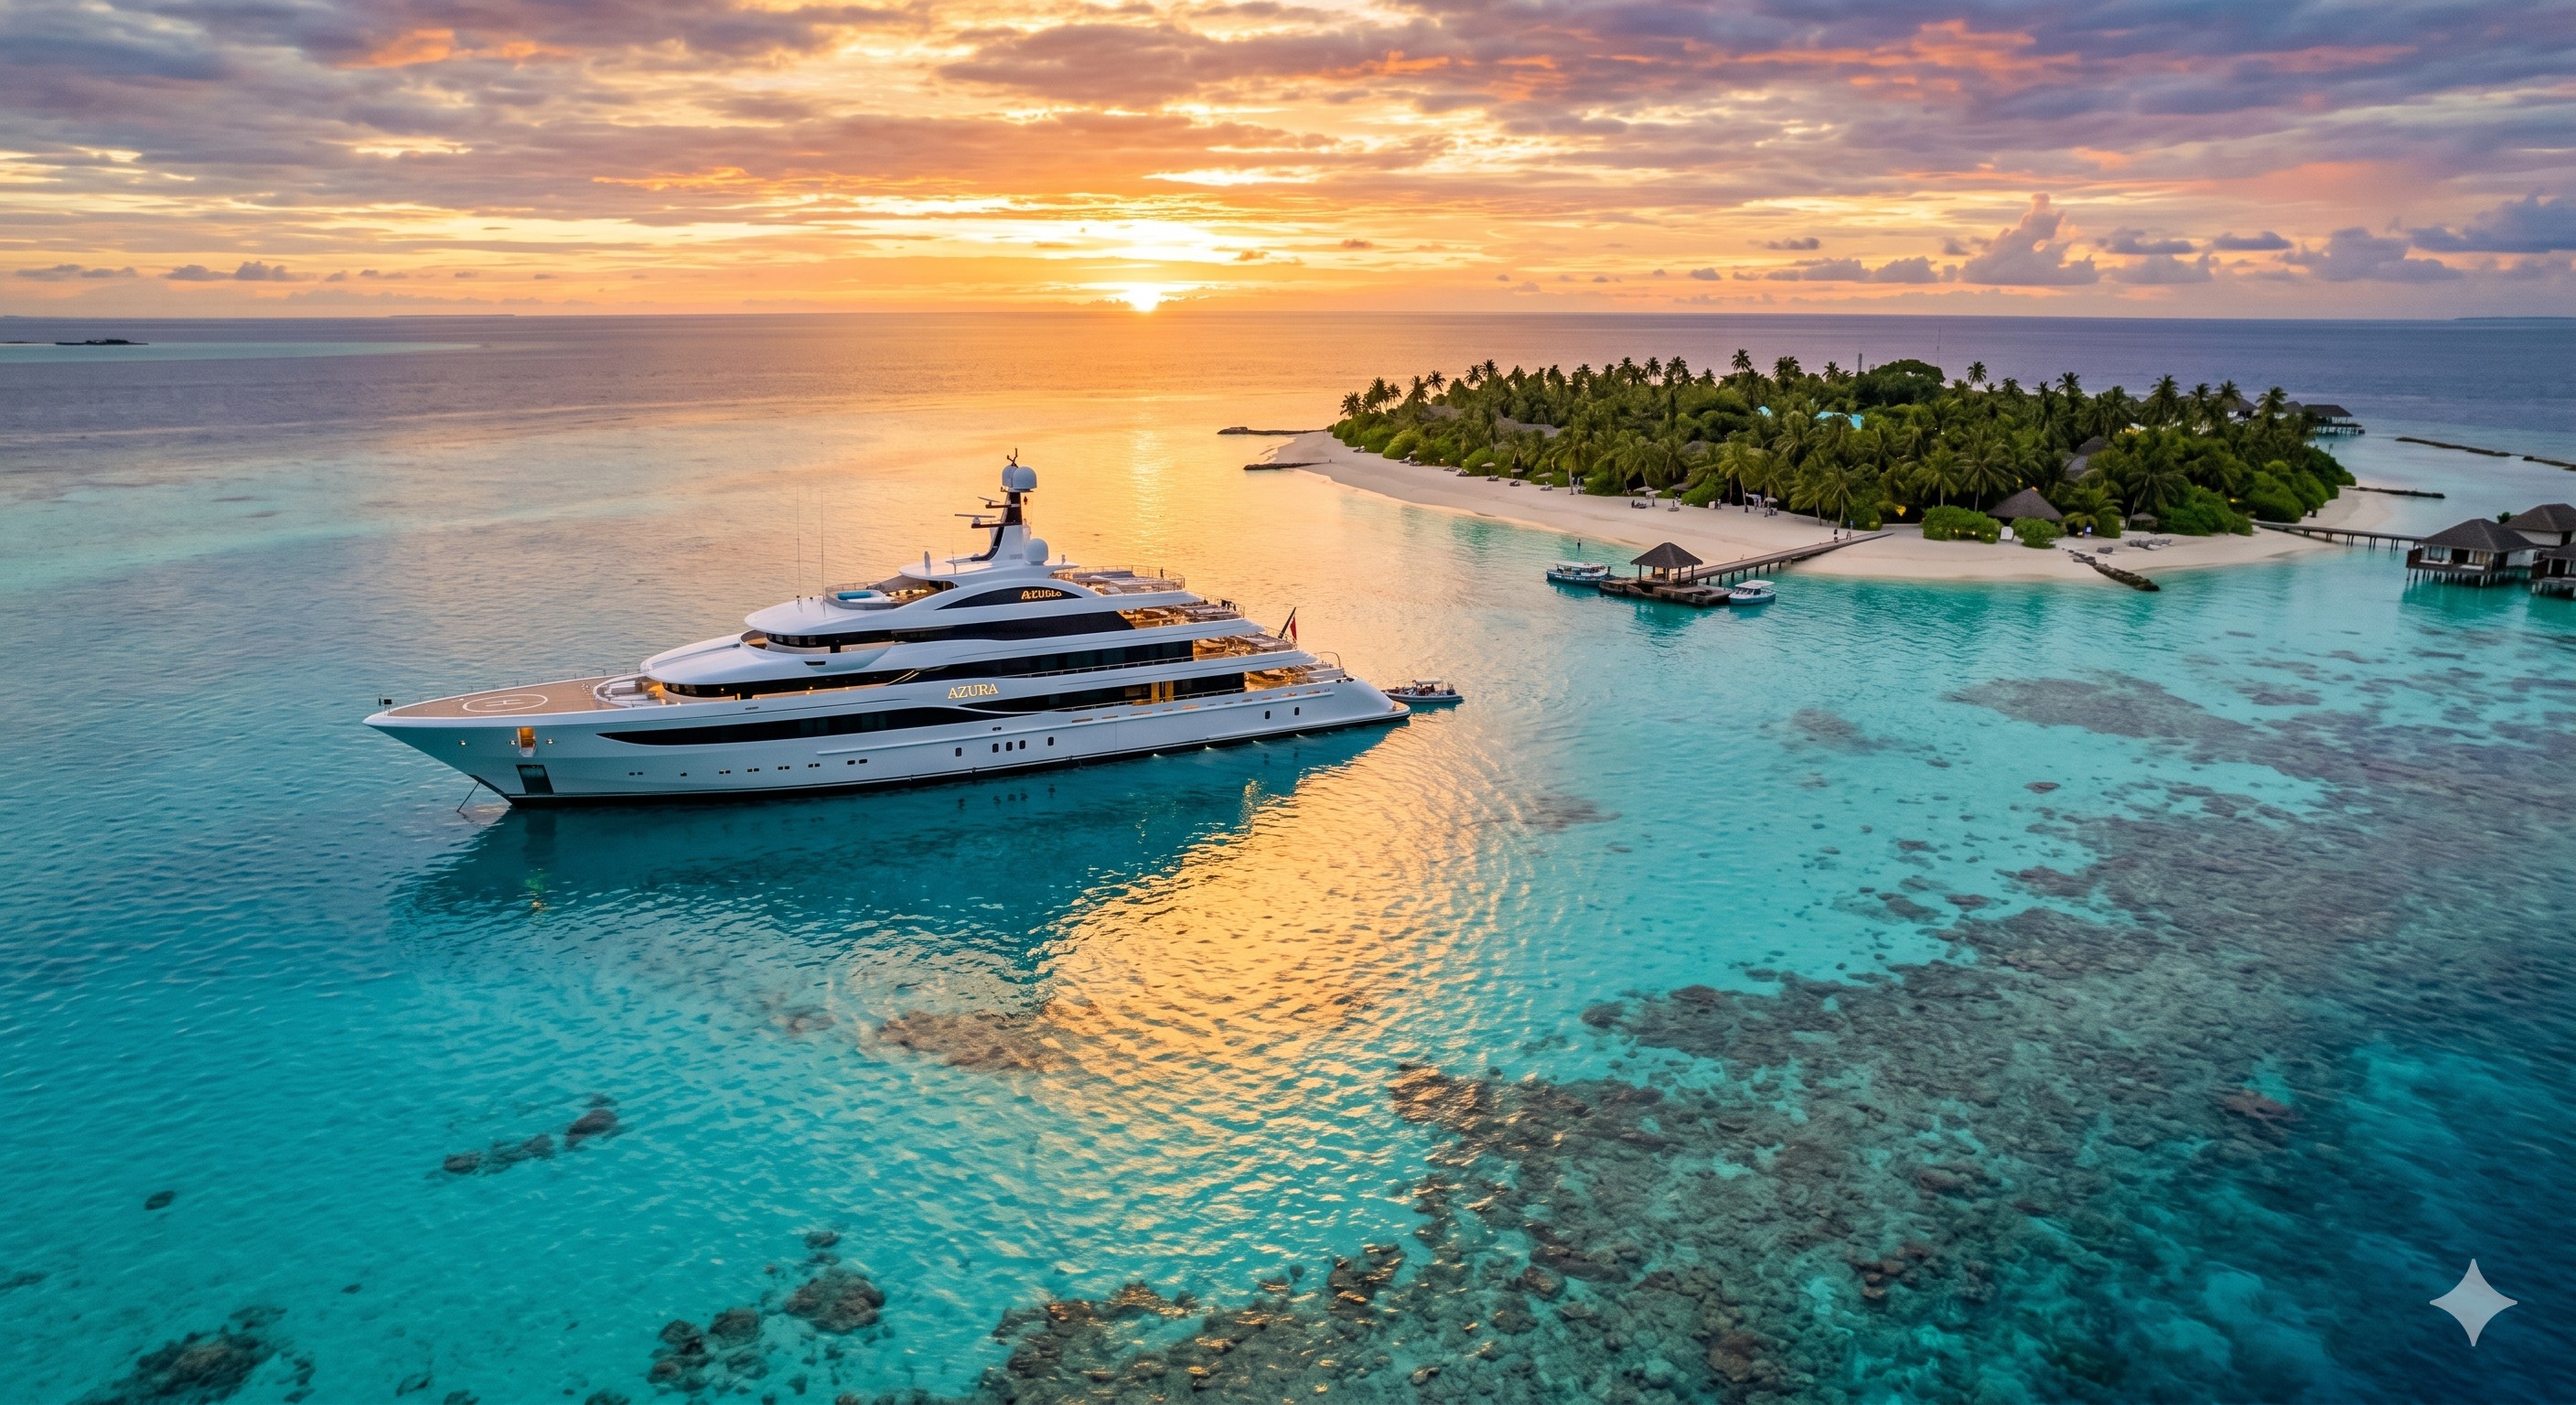
World-class superyachts and private resort properties across the Maldives, Hawaii, Mediterranean, and the Caribbean. Fully integrated with jet access — arrive wherever the destination, whenever you choose.

Fractional Ownership & Revenue Co-Management
Service 04 & 05
Fractional Ownership & Revenue Co-Management

Own a share of a private jet or yacht — enjoy the access without the full burden of sole ownership. When you're not using it, generate income through co-management with trusted operators. A new model of intelligent asset ownership.

Interactive Tool
Departing from Gimpo (GMP) —
Where Can You Go?

Select a jet category and model to see its maximum range, passenger capacity, and which cities you can reach non-stop from Seoul Gimpo Airport.

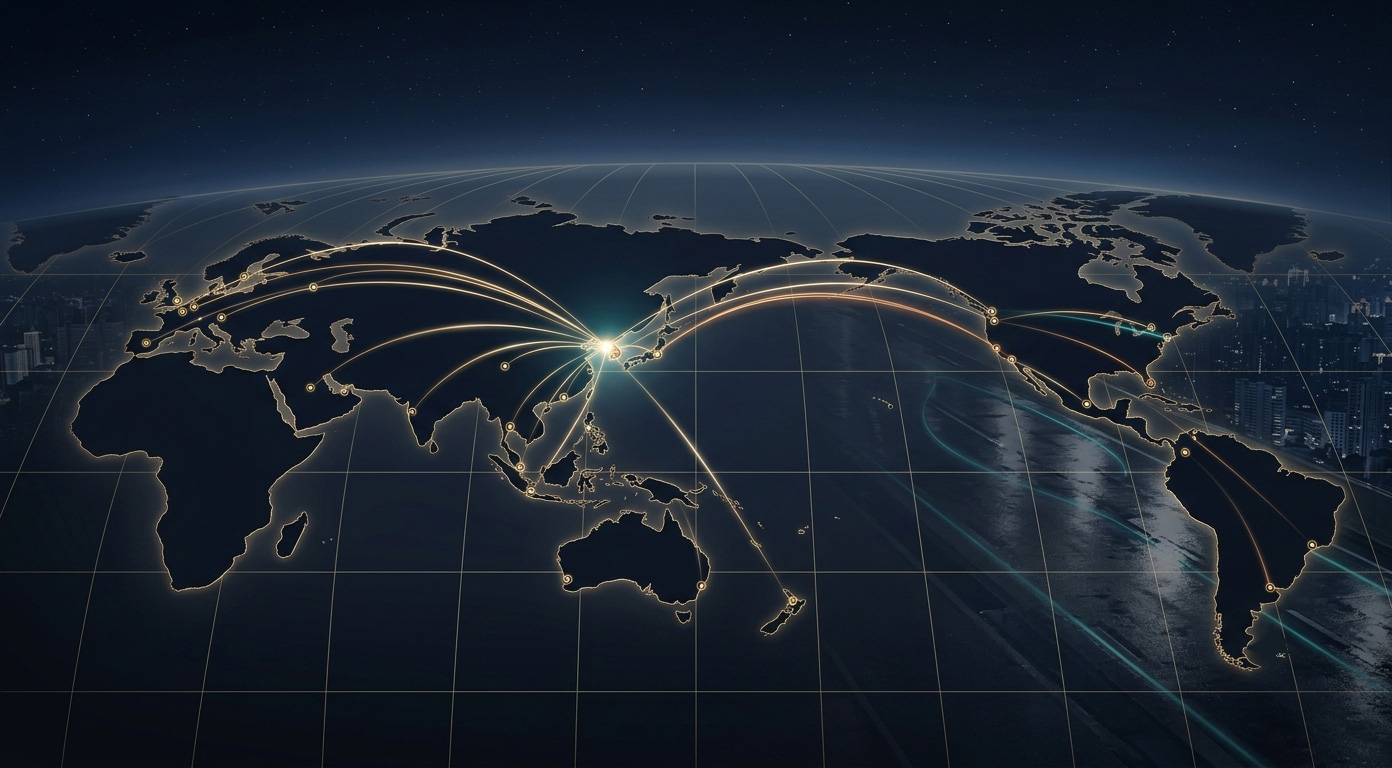
Global Flight Network from Seoul Hub
Reachability from Gimpo (GMP)

* Colored dots + lines = non-stop reachable. Gray dots = out of range. Reachability is calculated from precise great-circle distances — not from the visual map. Map uses equirectangular projection which distorts distances at high latitudes (e.g. North America appears further than actual). Always refer to the city list below for accurate reachability. Range figures: manufacturer published maximum under ISA standard conditions (NBAA IFR reserves). Actual range typically 85–90% of published. Departure: Seoul Gimpo (GMP) 37.5583°N, 126.7906°E

Interactive Tool
Global Visa-Free Access — 199 Passports × 199 Destinations

You know which cities your jet can reach non-stop. Now check which borders open without a visa — visa-free, visa-on-arrival, eTA and e-visa status for every passport, plus a two-country mutual check.

Open the Visa Tool →
Private Members — Trusted Network
Membership Platform

A trusted network.
Not a marketplace.

"The difference between Airbnb and a private members club is not the service — it is the trust. We are building the trust."

As agentic AI reshapes the brokerage industry, most intermediaries will be displaced. We will not. Our platform operates on a dimension AI cannot replicate: the trust between people of aligned values and shared standards.

When you are not using your aircraft or yacht, you can make it available to other members of the network — people you can trust, because they have been verified to the same standards as yourself. That trust changes everything:

This is not a technology platform disrupting an old industry. It is a new social infrastructure for the people who have always moved differently.

How This Differs from Existing Platforms
  • Airbnb / Uber model — anonymous, unverified, price-driven. Inherent quality and safety anxiety.
  • Our model — verified members, aligned economic profiles, trust-first. Assets shared within a known community.
  • The result: willingness to own, willingness to share, willingness to buy again.
The Global Lifestyle OS Ecosystem

Eight service layers.
One integrated life.

Private Jets of Korea is the mobility layer. But the Global Lifestyle OS goes further. Every service an UHNWI family requires during global movement — property, education, companion logistics, medical, security — is coordinated by a single platform, through a single relationship. Every sector leader does one thing. We do all eight.

Airbnb lists properties. NetJets operates aircraft. Nord Anglia runs 81 schools. Quintessentially provides concierge. Sollis Health operates medical services. Every one of them is a leader in their sector. Every one of them stops at their sector's edge. The Global Lifestyle OS starts where they stop — and connects everything they cannot.

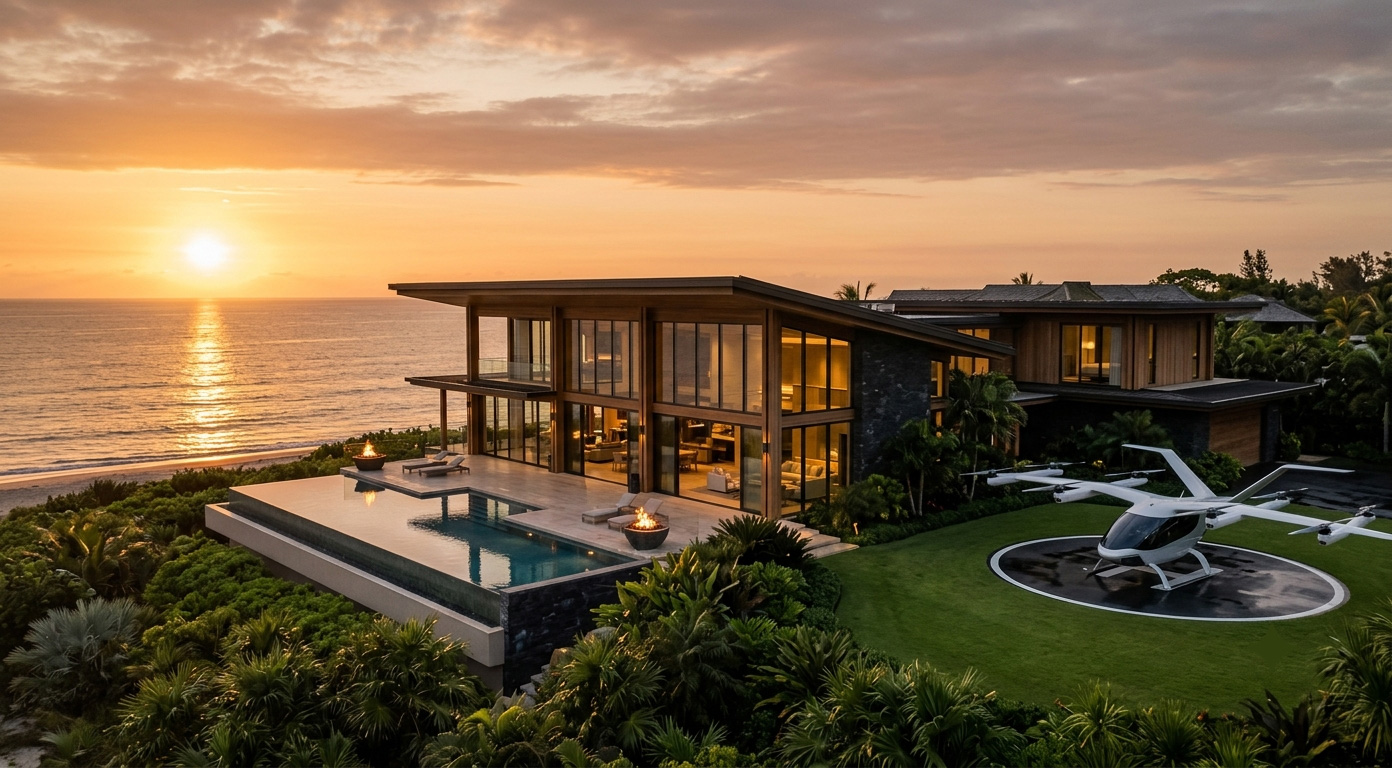
Property — Only one platform rents you the life.

Ultra-luxury beachfront estate — Hawaii Maui

The property is the address.
The life is what we deliver inside it.

Maui, Hawaii. 8 bedrooms, direct ocean frontage. 24-hour security. On-call medical response within 2 hours. Private chef, events, catering on request. From anywhere on earth, you — and your family, guests, pets, and equipment — can arrive by private jet.

Sotheby's sells the property once. Airbnb lists the booking. Four Seasons provides a world-class fixed address. The Global Lifestyle OS prepares a specific residence to the member's exact specifications before they arrive — and manages the life inside it indefinitely, across every property they own or rent, in every city they occupy.

Your business travels with you. Now, so does your life. 432 Park Avenue, Manhattan — corporate base, children's education continued, logistics coordinated. East Hampton — education, medical, chef, security. One platform. Every address.

Education — The world is the classroom.

AI Era International School — Fluid Campus

The single greatest constraint
on family freedom of movement — removed.

Education disruption is the leading reason executives decline overseas postings. The private jet is ready. The villa is booked. But the children's school holds the family in place. The Finest School eliminates that constraint permanently.

US elite private school–level education delivered via four modes — Physical AI tutor, online discussion with elite school peers, designated teacher home visit, and FBO Edu-Base campus. Anywhere. In any circumstances. Without interruption. 26 years of direct relationships with 100+ US elite private schools.

The world's first AI-integrated international school framework has been substantively agreed. H1 2027 signing.

Explore at thefinestschool.com →

Companion Logistics — The cargo travels with you. Not separately.

Companion logistics — pets, art, luxury goods

Same aircraft. Same cabin.
No separation.

Delta and United banned pets from cargo holds in 2026. Commercial aviation treats companion animals, fine art, confidential documents, and luxury goods as cargo — separated from their owners, subject to hold conditions, lost in airline bureaucracy. The Global Lifestyle OS treats companion logistics not as a problem to solve but as a service that flows naturally from private jet operations.

Pets fly in the cabin beside the owner, at all times. High-value artwork travels in a privately controlled environment with real-time owner monitoring. Customs, permits, and import/export clearance are handled end-to-end by the AI system — one coordinated process, not seven separate bureaucracies in seven countries.

The infrastructure is already there. The logistics revenue is created on top of it — with no additional large-scale investment required.

Medical & Security — 24/7 Across Every Node

Medical and security services

Safety that makes global living
genuinely viable.

24-hour security monitoring across all properties and mobile assets. On-call medical services at every node. Emergency air evacuation to appropriate medical facilities within 2 hours — from anywhere in the network. Aviation Week confirmed in October 2025 that FBOs are already integrating medical air evacuation services for survival — the Global Lifestyle OS extends this principle across the full spectrum of daily healthcare needs.

The AI backbone — NVIDIA, Hyundai, Boston Dynamics, Google — powers the monitoring layer. Physical AI deploys into UHNWI residences and FBO facilities outside the mass-market displacement regulations that are affecting every other sector. The life is ours. The backbone is theirs.

Integrated Mobility Ecosystem — The Future of Connected Travel
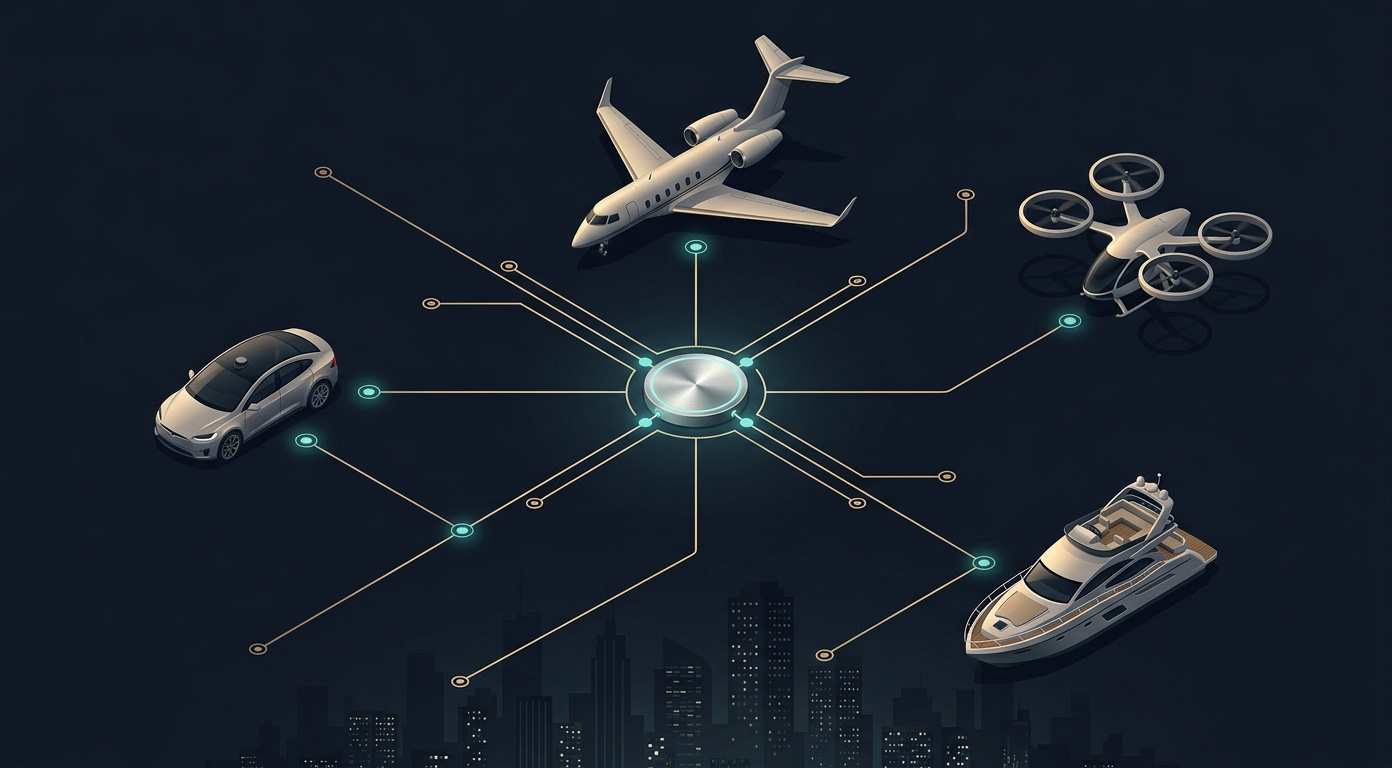
The Integrated Mobility Stack

Not a vehicle.
A complete coordinated journey.

"We do not fall into tech-solutionism — fixating on fragmented mobility technologies in isolation. We focus on market-responsive integrated services that connect and operate every element of what our clients need, organically. The mobility stack is not a list of vehicles. It is a complete, coordinated journey."

The Global Lifestyle OS integrated mobility stack spans six layers — from ultra-long-range private jets to FBO-to-destination last mile. Each layer operates independently at world-class standard. Together, they deliver a journey that no single-sector operator can replicate.

LayerServiceStatus
Ultra Long RangeG700, Global 7500, BBJ — 7,750nm non-stop. Cabin as office, residence, family space. Companion logistics integrated. FBO arrival guaranteed.Operational
RegionalPhenom 300E, Citation Latitude — city-to-city within region. 2,000–3,500nm. Korea domestic, Asia regional, European short hops.Operational
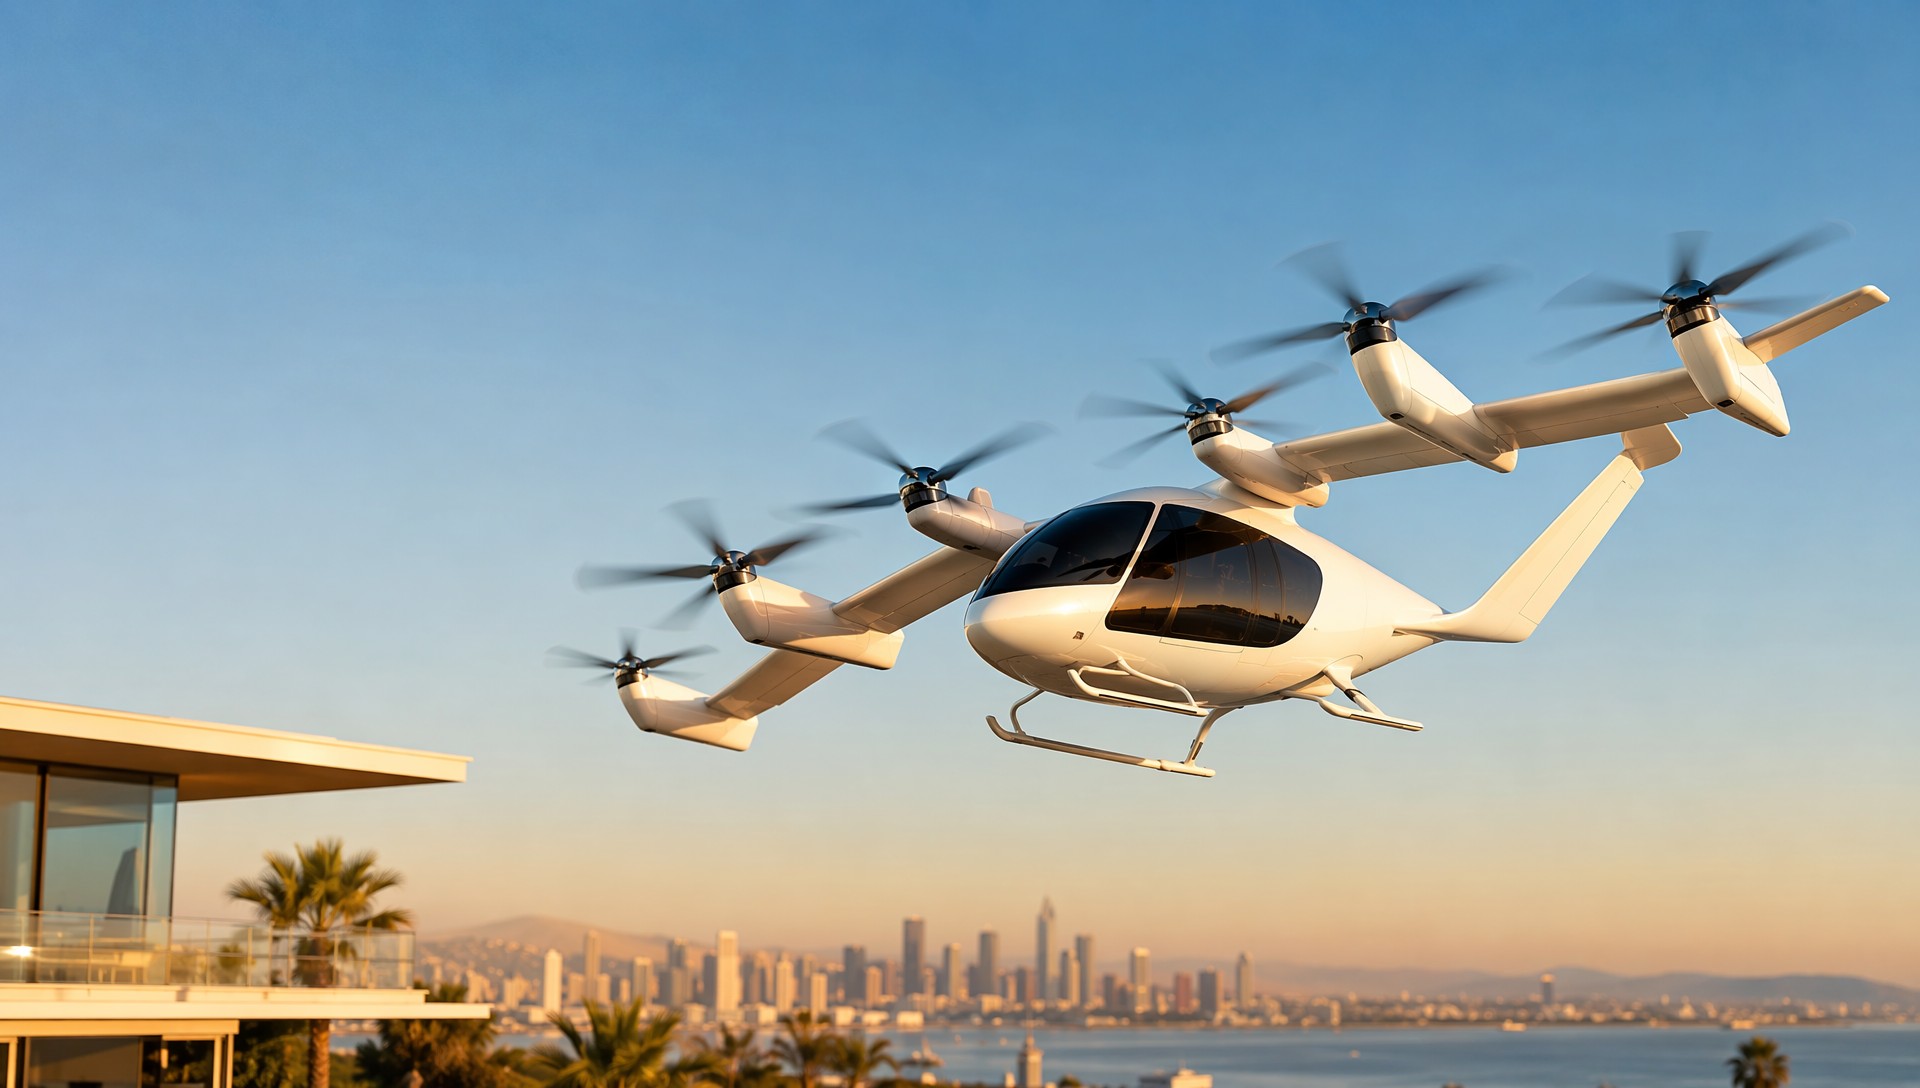
Last Mile — AireVTOL (Joby S4, Archer Midnight) — FBO to urban destination in minutes. Joby FAA Stage 4 certification cleared March 2026. The bridge between aircraft and final destination. Full eVTOL race analysis →2026–2027
Last Mile — GroundAutonomous Electric Vehicle — client's own AV dispatched and retrieved; curated premium AV partner; platform-owned premium AV. Dispatched at landing confirmation. No interaction required. Analysis: opportunity or disruption? →Selective · Expanding
Premium GroundChauffeur-driven vehicle — where AV is not available or where the member prefers human service. Always running in parallel. Member chooses.Always Available
MaritimeYacht / Private Boat — island and coastal destinations. Maldives inter-island, Mediterranean coastal, Hawaiian island-hopping. Coordinated from FBO Hub.Partner Network · On Request

The eVTOL Moment — What the Data Says

Joby Aviation has become the first eVTOL manufacturer to reach FAA Stage 4 type certification — the most advanced compliance milestone reached by any eVTOL company. Archer Aviation has been designated the exclusive air taxi provider for the 2028 Los Angeles Olympics. Korean Air has entered early eVTOL partnership. The technology is certifying. The question was never whether eVTOL would work — it was always where it fits in a complete mobility system. Our full race-to-market analysis covers Joby, Archer, EHang, and Eve Air Mobility in detail.

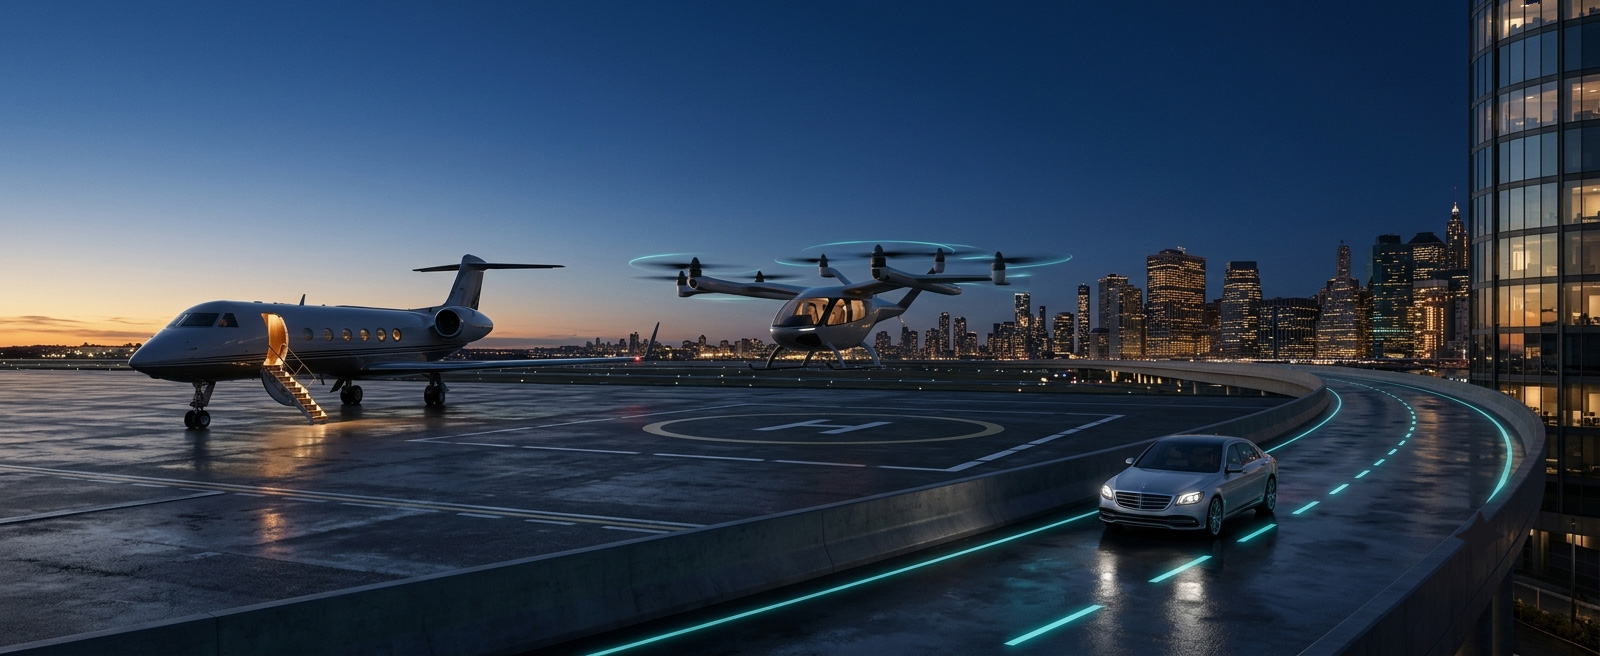
The Global Lifestyle OS does not own vertiports. It integrates eVTOL as the last-mile air layer — FBO to urban destination in minutes, coordinated through the same platform that managed the transatlantic flight that preceded it. The FBO is the vertiport. The system is already built. eVTOL completes the final gap.

Autonomous EVs — Our Position

Wood Mackenzie has identified 2026 as the inflection point for autonomous vehicles — a global driverless fleet projected to grow tenfold by 2030. Waymo is scaling to 27 US cities. Apollo Go, Pony.ai, and WeRide are simultaneously live across five Chinese cities. Read our full analysis: opportunity or disruption?

Mass-market robotaxi services serve the general public in prepared cities — no vehicle choice, no privacy guarantee, no customisation. By the standards of a Global Lifestyle OS member, that model is not viable. What is viable: the client's own AV dispatched at the precise time and location, or curated premium AV partners operating at the member's standard, not the platform's standard. The autonomous vehicle is not our product. It is our ground mobility layer — one of six in the integrated stack.

The Core Principle
  • Technology does not create markets — purposeful integration of technology does. The companies that will lead the next era of mobility are those who design the system, not just the vehicle.
  • eVTOL and autonomous vehicles have genuine, substantial value within an integrated mobility OS. As standalone businesses serving the general public — their viability is a genuinely open question. As layers in the Global Lifestyle OS — their role is clear and already designed.
  • This is Global Lifestyle OS — and its operational foundation is built here, at privatejets.kr.
Global Lifestyle OS — Worldwide Network
Global Lifestyle OS

This is where it begins.
This is where it leads.

Private Jets of Korea is the operational foundation — the five years of real-market experience that no investor can purchase and no competitor can shortcut. The Global Lifestyle OS is what it is building toward: the world's first hyper-personalised integrated mobility ecosystem platform. Private jets. eVTOL. Autonomous EVs. Luxury residences. AI-powered education. Companion logistics. Medical and security. All under one OS. All serving one client. All coordinated by one platform relationship.

The boundaries are collapsing. Home and hotel. Office and resort. School and transit. All converging into one. Every service exists separately today — private jets, education, logistics, property. No platform has unified them. 142,000 millionaires relocated in 2025. The world is moving. The question is whether you have the infrastructure to move with your life intact. Global Lifestyle OS is that infrastructure.

PlatformRoleStatus
privatejets.krMobility layer — the operational core. 5+ years field operations, Korea & Asia market knowledge, fleet access, client trust network. 42 aircraft types covering 82 cities from Seoul Gimpo.Operational
thefinestschool.comEducation layer — the family lock-in mechanism. Fluid Campus, US elite private school network, AI-era education anywhere via 4 modes. Framework substantively agreed with multiple US elite private schools.H1 2027 launch
zzoah.comMaster platform — Property OS, Companion Logistics, FBO Hub, security, medical, AI operations. The coordination point for every service. The single member relationship.Platform launch

The Position That Cannot Be Assembled Later

Maximum value. Minimum capital at risk. The Global Lifestyle OS does not build from scratch what already exists. 3,500+ FBO locations worldwide — the global FBO infrastructure already exists. GLO deploys into it. US elite private school relationships — 26 years of direct partnerships already built. The education infrastructure already exists. GLO deploys through it. The capital efficiency of this model is structural, not accidental: every investment anchors to market-verified assets with independent recovery value.

AI without the war. Every industry is fighting AI labour conflict right now. GLO was designed from day one to avoid it entirely — every partner is elevated by AI, not threatened by it. The Physical AI layer deploys into UHNWI residences and FBO facilities, outside the mass-market workforce displacement regulations that are causing conflict across every other sector.

For qualified partners seeking the full strategic architecture — the complete intelligence brief series covering the FBO model, the five-market strategy, the platform position, and the payment infrastructure — access is available by approved request.

Explore Global Lifestyle OS → AI Era International School →
Industry Intelligence

Markets we watch.
Signals that matter.

Each week we track the developments shaping private aviation, electric mobility, and the broader luxury transport ecosystem — the same markets that form the foundation of Global Lifestyle OS.

Compiled October 20, 2026  ·  Market Fundamentals · Ownership Models · Aircraft Programmes · Asia, India & Korea

Private Jet Market Fundamentals

Honeywell's Thirty-Fifth Outlook Puts the Next Decade at $343 Billion — 9,950 Jets, 4,200 Turboprops, a Fleet Up 29% and Flight Hours Up 34%

Honeywell Aerospace released its 35th Global Business Aviation Outlook on October 19, 2026 at NBAA-BACE, forecasting 9,950 business jet and 4,200 turboprop deliveries between 2026 and 2035 worth a combined $343 billion, a global fleet rising about 29% from roughly 39,400 aircraft in 2025 to nearly 51,000 in 2035, and annual flight hours up about 34% to 12.2 million.

The forecast is 4.4% higher than last year's for the same aircraft categories, with annual deliveries climbing from about 1,280 aircraft in 2026 to more than 1,500 by 2035 and the annual value of new deliveries passing $37 billion by the end of the period. Flight hours growing faster than the fleet is the detail worth holding: the same aircraft are being worked harder, which is a utilization story before it is an acquisition story. Jim Currier, Honeywell Aerospace president and chief executive, described owners and operators as "flying more, ordering new business jets, expanding their fleets"; Linnea Whisler, president of Commercial Original Equipment, called the coming decade "one of the most robust periods ever for business aviation." Current activity supports the claim rather than merely projecting it — business jet flying is up about 4% year to date, midsize and super-midsize up 7% and large cabin up 5% — and 32% of surveyed operators expect to fly more in 2027 against 11% expecting less.

Source: Honeywell Aerospace, October 19, 2026; AeroTime, October 19, 2026

Only 6–7% of the Existing Fleet Is Listed for Sale — and Large Cabins Take 61% of New Delivery Value

The same outlook puts just 6% to 7% of the existing fleet on the market, projects the midsize fleet to grow about 40% and the large-cabin fleet about 36% by 2035, and attributes 61% of the value of all new deliveries over the decade to large jets alone.

Three figures describing one condition. Supply of good used aircraft is effectively absent; the fastest fleet growth is in the midsize and large cabins; and the money is concentrated at the top of that range. Buyer priorities have moved to match — 85% of surveyed operators rank aircraft performance among their top three considerations, with cabin experience and operating and maintenance costs each cited by 55%. Kevin Schwab, Honeywell's strategic planning manager, put the shift plainly: "That's not to say cost isn't important, but it means that cabin comfort has come up in the buying decisions."

Why This Matters for GLO
  • A decade-long forecast in which flight hours rise 34% against fleet growth of 29% is a forecast of intensifying use, and intensifying use is where a platform earns — every additional hour flown is an additional ground leg, an additional arrival to receive, an additional day of the household to coordinate, and none of that is sold by the manufacturer whose delivery number the forecast actually measures
  • With 6–7% of the fleet for sale and 61% of new delivery value in large cabins, the acquisition problem for an Asian principal is no longer price discovery, it is candidate scarcity in exactly the segment that reaches Europe and North America without a stop — which turns the purchase into an advisory engagement running months before a contract, and that is work we are already doing
  • Cabin experience now ranking level with operating cost in buying decisions is the quiet confirmation of our entire thesis: the aircraft is being bought as a place to be rather than a means of arrival, and a client who thinks that way about the cabin thinks the same way about the terminal, the residence, the schooling and the care that surround it

Source: Honeywell Global Business Aviation Outlook via AeroTime, October 19, 2026

Ownership & Access Models

Fractional Flight Hours Forecast to Rise 96% — 850 Hours a Year Against 400 for Charter and 200 for Private Owners

Honeywell projects fractional operators' flight hours to rise 96%, nearly doubling over the decade — the fastest-growing utilization segment in the outlook — against average annual utilization of roughly 850 hours for fractional fleets, about 400 for charter aircraft and about 200 for privately operated aircraft.

The ratio is the argument. A fractional aircraft flies more than four times the hours of a privately owned one, which is why the segment compounds faster than the fleet that contains it. The survey underneath the forecast shows the migration already in progress: 14% of non-fractional operators already hold fractional shares and a further 16% are considering them, with half of those citing the need for more flying capacity rather than lower cost. Geographically the segment remains almost entirely North American — about 83% of global fractional flight activity originates at airports in the United States or Canada — which is to say the fastest-growing access model in business aviation has barely been exported.

Why This Matters for GLO
  • An owner at 200 hours a year and a fractional user at 850 are not two price points on one product, they are two different relationships with the same asset — and the one that grows 96% is the one where somebody else holds the operation, the crew, the maintenance and the schedule, which is precisely the function we are built to perform
  • That 83% of fractional activity still originates in North America is the single most actionable number in this week's edition: the model is proven, the growth rate is established, and the format has not yet been built for Asia — not because the demand is absent but because nobody has assembled the fleet, the operating approvals and the ground infrastructure on this side of the Pacific
  • Half the operators considering a fractional share name capacity rather than cost, which means the buyer we will meet is not trading down from ownership but adding to it — the two-directional growth we described in the last edition, and the reason the counterparty needs one platform holding both rather than an owner's management company on one side and a broker on the other

Source: Honeywell Global Business Aviation Outlook via AeroTime, October 19, 2026

Aircraft Programmes

Gulfstream Adds a Fourth G400 and a Third G300 to Flight Test — and Declines to Name a Certification Date

At NBAA-BACE on October 19, 2026 Gulfstream confirmed a fourth G400 has joined flight test, including the first aircraft with a full interior which flew from Dallas Love Field, while the third of three planned G300 test aircraft is being assembled by licensee Israel Aerospace Industries in Tel Aviv and the second was expected to fly "very soon."

Mark Burns, Gulfstream's president, was unusually direct about what he could not say: "We don't have a prediction on when [it will be certificated]. Unfortunately, I don't make that call." The G400 first flew in August 2024 and was originally intended to deliver in 2026; the delay is attributed to tightened regulatory requirements, software validation in particular. The aircraft itself is not the problem — Burns reported a recent flight of about 3.5 hours at roughly 48,000 feet and a G400 test aircraft has already set a Miami city-pair speed record at 4 hours 8 minutes, averaging Mach 0.89. G300 deliveries remain provisionally set for 2028.

Why This Matters for GLO
  • A manufacturer with Gulfstream's record declining to forecast its own certification date is the same signal we read in the eVTOL programmes last edition, arriving now in the conventional fleet: safety verification in the advanced economies is tightening across every category of aircraft, and schedule risk has moved from the airframe to the paperwork
  • For a client, that converts a delivery slot into a planning hazard — an aircraft ordered against a 2026 date and still uncertificated in late 2026 leaves a household with a travel requirement and no asset, which is a gap that has to be bridged by charter and management rather than by patience, and bridging it is a platform service

Source: Aviation Week and FlightGlobal, October 19, 2026

Asia, India & Korea

India Posts Asia-Pacific's Largest Fleet Gain — and Korea Closed 2025 With 21 Business Jets

Honeywell's regional commentary on October 20, 2026 identified India as the strongest business jet fleet growth in Asia-Pacific at about 295 aircraft by the end of 2025, driven by expanding wealth, airport infrastructure and the GIFT City leasing initiative, with China limited to "selective premium and fleet-renewal opportunities" — while Asian Sky Group's year-end 2025 registry count puts South Korea at 21 business jets, down one on the year, against Australia's 218, Japan's 86 and India's 188 on the same basis.

The two India figures differ because the counting bases differ — Honeywell surveys operators across all business aircraft, Asian Sky Group counts jets by registry — and the direction is identical in both: India added the largest net number of aircraft in the region and South Asia recorded the highest subregional growth rate at 10.3%, while the Asia-Pacific fleet as a whole grew 1.5% to 1,168 aircraft in what the report describes as "a gradual recovery rather than a sharp expansion." Within that, Greater China stabilised after four years of decline, Singapore posted the region's largest net loss at minus ten, and Vietnam grew fastest of any country — 15 aircraft, up six, a 66.7% increase. Korea does not appear in Honeywell's Asia-Pacific commentary at all.

Why This Matters for GLO
  • Read the whole industry's attention and it points one way: in the broad frame the market everyone is watching is Asia, and as a single country India is now treated as the largest growth opportunity on earth — 295 aircraft, the region's biggest net gain, a 10.3% subregional growth rate and an explicit policy and leasing structure behind it, which is what a market looks like when access models and regulation stop obstructing capital that was already present
  • Korea is the anomaly inside that picture, and the anomaly is the opportunity. Twenty-one business jets, down one, in the world's twelfth-largest economy — a country with global-scale manufacturers, the capital in quantity, and a resident population of principals whose overseas obligations are not optional. Vietnam, at a fraction of Korea's GDP, holds fifteen and grew 66.7% in a single year; Japan holds eighty-six; Australia holds two hundred and eighteen
  • A twenty-one-aircraft fleet in that economy is not a measure of demand, it is a measure of suppression — and we have been specific throughout this year about what suppressed it, because it was never affordability. It was disclosure risk, an unresolved environmental objection now answered by sustainable aviation fuel, a regulatory asymmetry in semi-private operation that has no equivalent in the comparator markets, and the absence until 2028 of a dedicated business aviation terminal at the country's principal international gateway
  • Every one of those constraints is being removed inside this decade, which is why the industry consensus we share is that Korea — the market most conspicuously behind relative to the size of its economy — is the market that compounds at the highest rate from here. A fleet of twenty-one does not grow by percentages that look like Australia's; it grows by multiples, because it is starting from a base that bears no relationship to the wealth sitting behind it
  • And a market that grows by multiples from a base of twenty-one is won by whoever is already holding the client when the constraints lift, not by whoever enters once the growth is visible in the data — which is the entire reason the platform, the FBO model and the eight-layer service stack are being built now rather than announced later
Global Lifestyle OS · Our Differentiated Advantage

This week the industry published its own ten-year view and it agrees with ours on every structural point. Demand intensifies rather than merely expands — flight hours up 34% against a fleet up 29%. Value concentrates at the top — 61% of new delivery value in large cabins, with 6% to 7% of the existing fleet available to buy. The fastest-growing way to hold an aircraft is the one where somebody else operates it, at 96% growth and 850 hours a year against 200 for private owners. And the region the entire forecast is watching is Asia, with India named as its single largest growth market. None of those four conclusions describes an aircraft. All four describe the layer above the aircraft.

Korea's twenty-one aircraft is the number to sit with. It is not a small market; it is a suppressed one, and the four things that suppressed it — disclosure risk, the environmental objection, the semi-private regulatory asymmetry, and the absence of a business aviation terminal — are all being resolved within this decade. India is the proof of what happens next: the aircraft did not appear because Indian wealth was created in 2025, they appeared because access models and policy stopped standing in the way of wealth that already existed. Korea is at the same door with more capital behind it and fewer aircraft in front of it. The forecast that leaves Korea out of its Asia-Pacific commentary is not describing the absence of a market. It is describing the absence of anyone having built the thing the market needs in order to appear.

That thing is documented rather than aspirational. The Corporate-Customised FBO Operating Model — the world's first — replaces the shared-terminal premise with dedicated corporate suites carrying an eight-layer service stack: board-level hospitality, a 24-hour resident physician, AI-integrated education from nursery through Grade 12, eVTOL and autonomous EV infrastructure designed in from the outset rather than retrofitted, companion logistics, and suite-based security. It targets more than 60% non-aviation revenue, which is the mechanism that makes a Korean regional airport viable on day one rather than on the day the traffic arrives. Sixteen chapters, applied in detail to Korea's airports and to Korea's specific regulatory asymmetry in semi-private aviation. Honeywell's outlook tells you how many aircraft the next decade will produce. It cannot tell you who will be holding the client when Korea's twenty-one becomes two hundred. That is a different question, and it is the only one we are working on.
Contact & Enquiries

Ready to move
differently?

Whether you are chartering for the first time, exploring aircraft acquisition, or interested in our membership platform — we are here.

Private Jets Korea — Concierge Service
Existing Members

Please contact your dedicated manager directly. Your manager's details are on file — reach out to them by the channel you have established.

New Enquiries

For all new enquiries — charter, acquisition, membership, or general information:

[email protected]

Please indicate in your subject line whether your enquiry is Urgent or General — this helps us prioritize and respond appropriately.

Response Times
Urgent
24 hours · Immediate response around the clock
General
Within 30 minutes · 9:00 AM – 6:00 PM (KST)